
The Deceptive Reasons IRA and 401K Plans Exist

You are about to read some statements in conflict with your long held beliefs about the benefits of traditional IRA and 401K plans. Chiefly, there are some major negative issues with traditional tax-deferred IRA and 401k plans. These statements may contradict with what you have been convinced to believe by your employer, Corporate America, Banks, Wall Street advisors, and retirement planners. Please keep an open mind and realize that some of your financial beliefs may come from sources that have their own motives not necessarily aligned with your own. Nor are they aligned with the current reality of the U.S. federal debt situation. Sometimes not following the crowd is the best choice. 401k plans were created to save money for employers not just for your benefit. Please keep that in mind.
Table of Contents
IRA and 401k Plans Were Not Created Solely for Employees’ Benefit
Before 1970, most Americans had strong pensions designed to meet a good deal of their retirement income needs. Many companies, unions, state and county governments, and other organizations provided pensions as an inducement toward employee loyalty and recruitment. Most of the federal, state and county pension plans still exist. However, for the rest of us, pensions have mostly become a thing of the past.
Corporate greed was changing the landscape.
IRA and 401k Plans Were Created to Save Money for Corporations
By the 1970s, at the height of strong unions negotiating for larger retirement pensions, corporate America was becoming inundated with pension liabilities that grew beyond corporations’ ability to support. Growing longevity also contributed to the liability. Corporate America appealed to congress for help.
In response congress passed the Employee Retirement Income Security Act of 1974 (ERISA). Among other provisions this act started the traditional IRA or Individual Retirement Arrangement (also known as IRS code 408a). This was the first act of Congress that attempted to shift the retirement funding onto individuals instead of corporations.
The public happily accepted this IRA tax law as a savings advantage. The public did not fully understand how their retirement funding responsibility was shifting from their employer onto themselves.
Corporations, banks, and investment firms were all happy to see these changes.
By pushing what was traditionally the corporate pension responsibility off onto the employees, corporations could save massive amount of money. Thus, they pushed questionable benefits of tax deferred into the public mindset.
Along Came 401k Plans
But IRAs were not enough. Under further pressure from corporate America, congress passed the Revenue Act of 1978, including a provision — Section 401(k) — that gave employees a way to tax-defer compensation. The law went into effect on January 1, 1980
Corporate America immediately started pushing 401(k) plans to their employees. They sold it as an employee benefit. Somehow employees accepted this as an employee benefit instead of corporations unloading pension-funding responsibility onto employees. What a deception!
Corporate America discovered that employees were more interested in their 401(k) than their pension. Possibly because employees could more easily see the account balances which provided a “glitter effect”. Possibly because employees believed they were saving on taxes and did not understand they were simply delaying taxes and allowing the tax debt to the IRS to grow for decades.
Perhaps small employer matching contributions to these plans further tricked employees into liking their 401k plan. The concept of “free-employer-match” was more appealing than noticing the pension reductions, regardless of how insignificant the small match was. Perhaps because employees had more control of their 401(k). Maybe the employee just did not understand that their pensions were worth more than their 401(k)s.
Regardless of the reason, the corporate trend over the past few decades has been to reduce employer cost by pushing employees to rely on employee funded 401(k), 403(b), and 457 type programs. This is a backhanded way to shed the responsibility and cost of employee retirement.
Unfortunately, the American public fell for this scam and seemed to be happy funding their own retirement through 401k plans. We wish we could shout loud enough for everyone to hear “SNAP-OUT-OF-IT!”
Listening to their poor friends and poor co-workers around the water cooler, praising their 401k, is apparently more convincing than hearing the advice of wealth managers. So convincing is this advice from friends that they ignore the highly limited investment choices and inflexible rules of most 401K plans. Most 401k plans have extremely limited liquidity. What good is money you can’t get to?
Why would you let corporate America convince you to place money in a plan that you cannot spend for many years. It’s nuts!
Unfortunately, corporate America and short-term thinking CPAs have been convincing much of the American public for years that IRAs and 401(k) tax-deferred plans are a good thing. But what if this is simply not true? Banks, financial firms and employers all benefit from us believing in this tax-deferral nonsense.
Paying taxes now, on the smaller seed makes sense versus paying taxes on the much larger crop later in life after your tax-deferred crop has grown larger and when tax-rates are much higher.
Paying taxes now when tax rates are historically low makes good sense. Delaying taxes in a tax-deferred account until tax rates are higher is moronic. Thus, tax-deferred IRAs and 401(k)s are a hoax.
Why do Banks and Financial Firms Promote Tax-Deferred Acconts?
Your tax-deferred account including IRAs and 401k plans accumulates larger and faster than after tax accounts. This is because these accounts include not only the money that belongs to you, but also tax-deferred money that the IRS has a future tax claim on. The part of that retirement account that actually belongs to you depends on future tax rates and your future tax bracket. However, you are paying management investment fees on the entire balance of that IRA or 401k plan. Not just the part that ultimately belongs to you after taxes. From a retirement planning viewpoint, this implies that you are paying management fees to grow the IRS future share of your retirement balance. How do you feel about paying management investment fees to grow the IRS future share of your retirement account?
Investment managers are happy to collect fees from you on money that may not actually belong to you in the long run. Are you also happy about this happening? Do you believe you have a no fee retirement accounts? Do you believe financial firms build their fabulous office buildings without collecting fees? Do you also believe in Santa Claus?
Roth accounts include more than just tax-deferred advantages. It rules are properly followed, Roth account can both grow and be distributed without taxes. Possibly the best solution in to get rid of the tax-deferred balance in your retirement account by converting to a Roth. Then, if you follow Roth distribution rules, you will no longer be paying management fees on money that could ultimately belong to the IRS.
Note that your tax-deferred balance may also include money potentially belong to the state that you live in.
The Tax-Deferred Hoax
CPAs are praised and encouraged by their clients for saving current year’s taxes while ignoring future taxes. The public at large buys into the tax-deferred deception because corporate America and Wall Street promote a lie. They tell employees that they will be in a lower tax bracket when retired.
Tax-deferral only makes sense if taxes will be lower in retirement. But in our opinion, this is highly unlikely.
In 30 plus years of helping many people through retirement, I have never experienced a client being in a lower tax bracket in retirement. Never!
Are lower taxes in retirement a hoax?
Corporate America and Wall Street like to point out that you will have no employment income in retirement and thus you will be in a lower bracket. But it is in their profit interest for you to believe this propaganda. The truth depends on how much of your retirement income comes from pensions, social security, tax-deferred accounts and your retirement spending.
In our opinion, what really controls your taxes in retirement is your retirement spending and where the money comes from to support that spending. For many people retiring today, that money comes from tax-deferred accounts, IRAs, 401(k)s, and pension that are fully taxable. That is because most people have the vast majority of their retirement savings in tax-deferred accounts like IRAs, 401(k)s and pensions.
In addition, 85% of the money coming from a Social Security payment is taxable for most people.
The Real Issue is How Much You Spend in Retirement
Ask yourself when do you spend more money, during a normal day or a day on vacation. The clear answer for most people is they spend more on a vacation day. Similarly, you will likely spend considerably more in retirement. After all, retirement is a perpetual vacation!
As you spend more you will push yourself into a higher tax bracket.
People often have delayed desires that they immediately pursue once in retirement. This comes at a financial cost. They spend money on vacations, hobbies, golf, home renovations, exotic travel, that car they always wanted, the new beach house, the travel RV, spoiling their grandkids, and other desires.
Now that they are retired and have time to spend money, they often spend more in retirement. Where does that money come from … withdrawals from tax-deferred accounts, IRAs and 401(k)s. All that spending pushes them into higher tax brackets.
We refer to this problem as retirement tax bracket creep.
Tax Rates are Highly Likely to Increase in the Near Future
Again, tax-deferral only makes sense if taxes are going to be lower in the future. But that is not likely! At every seminar or lecture we ask the audience how many think taxes will be going up. We typically get a unanimous show of hands.
If people strongly believe taxes are going up, why are they delaying taxes through tax-deferred accounts? Do they wish to wait until taxes are higher to pay them? Have people been brainwashed into thinking tax-deferred is the right path? Maybe if people better understood how high taxes can get in the future, they would convert tax-deferred accounts.
Past Tax Rates Can Hint at Our Future
Past tax rates can help us understand where taxes are headed in the future. From 1936 until 1981, when Reagan got elected, the top federal tax bracket rate was at least 70 percent at all times.
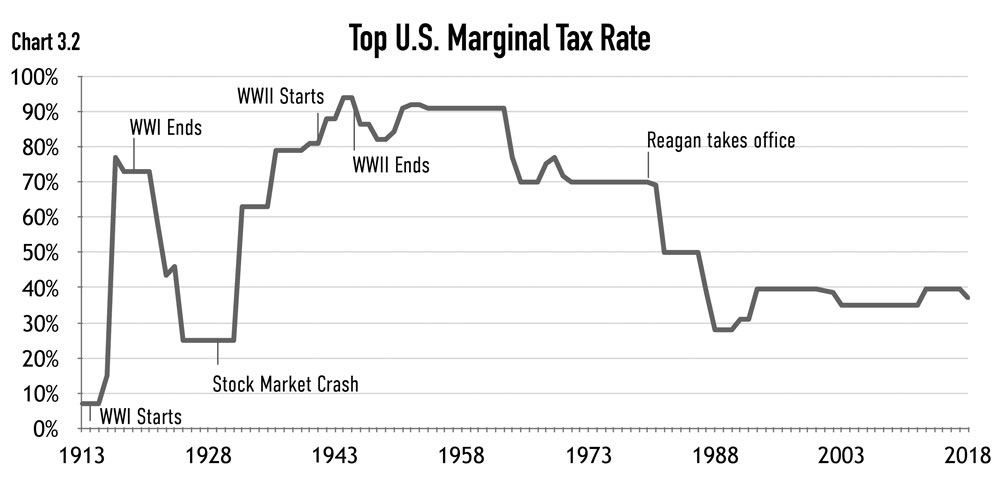
Could you imagine paying 70% tax on your retirement withdrawals? This tax rate existed not that long ago in our parents’ or grandparents’ era. And remember, history has a habit of repeating itself. Imagine state taxes on top of these high federal taxes!
When you think about this nation’s debt, over 39 trillion as of the summer of 2026, much higher taxes are almost certainly coming. Why would you even consider deferring or delaying paying taxes when taxes are on sale now?
The Gas Price Example
Think of it this way: would you stop and fill up at a gas station advertising 99-cent-per-gallon gas? Of course you would! Gas is on sale! We know we will need to pay for gas anyhow. Let’s load up now, when it is on sale!

But when taxes are on sale, like they are today, why do people hesitate paying taxes. What keeps people from paying taxes when they are on sale? We love to buy things when they are on sale. However, we fail to take advantage of the “tax sale” opportunity we have now. We don’t avoid taxes by not paying them. We just delay paying them. And as we delay paying taxes, the tax bill is growing with the growth within the tax-deferred account. Plus, in our opinion, it is almost certain that rates will soon be increasing. Why not pay taxes now by doing Roth conversions, while taxes are historically low?
Why do people not understand that, with tax rates at their lowest in decades, taxes are “on sale”?
If you convert your tax-deferred account to a tax free forever account, like a Roth IRA, then you no longer need to worry about these future higher tax rates. You pay taxes at today’s discounted tax rates. Further, you remove worry about Required Minimum Distributions, RMDs, from your tax-deferred account. See a qualified professional retirement planner about the best ways to do conversions as it does require multi-year planning to accomplish this efficiently.
The Noise About Tax-Deferred Compounding
There is much deception about the advantages of tax-deferred compounding. Yes, deferred compounding does help the growth. Not paying capital gains taxes, as you sell investments within your tax-deferred account, does increase your gains, as you have a larger balance to reinvest after a sale with deferred tax liability. Thus, tax-deferred balances can grow faster. But how much faster is affected by the frequency of sales being modeled and other assumptions. In other words the effect of compounding is a matter of opinion.
However, you have a debt to the IRS which is also growing as fast as the total account. And that debt will be paid at future future, unknown but potentially higher ordinary income tax rate. Both the after tax money that is truly yours and the potential debt due the IRS are growing. One balance does not help or affect the other. The question is whether the benefit of tax-deferred growth outweigh the future tax rate increase risk, and the lack of access, and flexibility inherent in a tax-deferred account? We don’t know how much of this traditional tax-deferred account will be claimed by the IRS in the form of higher taxes.
Instead of a combined tax-deferred balance growing, it is better to have your own balance growing in a tax-free account (such as a Roth account) without dragging along the balance owed to the IRS. Think of a traditional tax-deferred account, such as an IRA as an IOU to the IRS. Getting rid of this tax debt while taxes are low is a wise business decision.
The bottom line is “you can’t out-compound the tax-debt” that is growing.
The Noise About “Opportunity Cost”
Contributing money to an IRA or 401k account does reduce your current year taxes. But the taxes-due do not evaporate. You still owe the taxes. And these taxes grow with your IRA or 401k balances. You are borrowing money from the IRS to be paid in the future at an unknown amount when you make withdrawals from your account. Both the growth is unknown and the unknown future tax-rate you must pay. So much uncertainty!
Some advisor point out that if you don’t take advantage of current year tax-deferral that you are missing an opportunity to invest the tax-savings. Let’s say you invest that current year tax saving of taxes in an investment. If so, how certain are you that your investment will outgrow your future tax liability? Remember the borrowed money from the IRS (sometimes called the tax savings) will need to grow faster than your tax-deferred balance and cover future higher tax-rate increases?
Retirement Planning Fundamentally Involves Reducing Debt
Most people are concern about taking on debt. However, they don’t recognize they are taking on debt with every contribution to a traditional IRA or 401k. That debt is the future tax debt owed to the IRS and possible the state. It is scarry that corporations and Wall Street have convinced us that taking on this tax debt is somehow wise or a good retirement saving plan. Again, in our opinion, what a scam!
Most people avoid debt and try to pay down debt if they have debt. Why is debt to the IRS viewed differently?
Most people would not take on debt in order to make an investment. However, they would contribute to an IRA or 401k in order to temporarily save on taxes. We hope you see that this tax-deferred retirement strategy is faulty. How did we allow our financial thinking to become so perverted?
Opting for a Roth account instead of a traditional tax-deferred account (IRA or 401k) is not an opportunity cost.
It is a rejection of debt to the IRS.
Your Silent Partner
If opening a business with an unrelated partner, would you insist on a document or an agreement regarding how much of the business you own versus your partner? Any business person would wish to know the ownership share of the partnership. To do otherwise would be ill-advised.
Most people do not realize that when you contribute to an IRA or 401k, you are entering into silent business partnership with the IRS and the US Congress. Thus, your silent partner can change how much of that account belongs to you and how much belongs to the IRS on a whim. They change that partnership agreement every time they change tax rates. How much do you trust your silent partner?
Escape this financial madness by not making further contributions to an IRA or 401k and by taking action to convert to tax-free accounts such as ROTH accounts. Talk to a professional retirement planner such as a CFP and CPA about how to best plan this transition to the tax-free account.
By the term 401(k) we cover similar employer-sponsored retirement accounts such as 403(b) 457, 401(a) Etc., SEP IRAs and Simple IRAs.
Key Takeaway Regarding Tax-Deferred Retirement Savings
The central message of this web page is that successful retirement planning is about much more than simply accumulating money in a 401(k) or IRA. While tax-deferred retirement accounts can be useful savings tools, they also create future tax obligations that many investors fail to consider.
We encourage readers to look beyond the immediate tax deduction and ask a more important question: What will my taxes look like when I actually need this money? If future tax rates are higher—or if higher retirement spending pushes you into a higher tax bracket—the tax savings received today may be outweighed by larger taxes later.
Rather than focusing solely on growing retirement assets, this web page emphasizes the importance of managing lifetime taxes. It suggests that strategies such as Roth contributions or Roth conversions may provide greater tax certainty by paying taxes at today’s rates and allowing future qualified withdrawals to be tax-free.
Ultimately, this web page encourages readers to view retirement planning as a comprehensive process that includes tax planning, income planning, and long-term financial strategy—not simply investing as much as possible in tax-deferred accounts. Because every person’s financial situation is unique, this web page recommends working with qualified financial advisors and tax professionals to determine the most appropriate retirement strategy.
FAQ: Understanding the Claims About IRAs and 401(k) Plans
1. What is the main message of this web page?
Traditional IRAs and 401(k) plans are often misunderstood. These accounts primarily shifted retirement funding responsibility from employers to employees and that tax-deferred savings create higher tax burdens later in retirement.
2. Is a 401(k) plan alone a retirement plan?
No. A 401(k) is only a retirement savings vehicle, not a complete retirement plan. A comprehensive retirement strategy should also address taxes, income planning, investment allocation, healthcare costs, and estate planning. A traditional 401(k) plan may increase taxes in retirement.
3. Why were IRAs and 401(k)s created?
Congress introduced these plans in response to increasing pension liabilities faced by employers. These accounts allowed companies to gradually shift retirement funding responsibility from employers to employees. These plans are marginal employee benefits, and major employer cost cutting attempts.
4. What is ERISA?
The Employee Retirement Income Security Act (ERISA) of 1974 established important protections for retirement plans and introduced the framework for Traditional IRAs. ERISA was the beginning of the transition from employer-funded pensions toward individual retirement savings.
5. What is the major problem with tax-deferred retirement accounts?
Tax-deferral postpones taxes rather than eliminates them. Investors may ultimately pay taxes on larger account balances and potentially at higher future tax rates. ROTH account may be a better choice.
6. What is meant by “tax deferred”?
Tax-deferred accounts allow contributions and investment earnings to grow without immediate taxation. Taxes are paid later when money is withdrawn from the account. However, taxes paid later are at an unknown rate. The taxpayer could be in a higher bracket and with higher tax rates. Paying taxes later is a huge risk with multiple unknowns. Why take the risk when taxes are historically low now?
7. Why do we believe many retirees will be in a higher tax bracket?
Once retired, people have time to spend money on vacations, hobbies, golf, home renovations, that car they always wanted, the new beach house, the travel RV, spoiling their grandkids, and other delayed desires. Where does that money come from … withdrawals from tax-deferred accounts, IRAs and 401(k)s. All that spending pushes them into higher tax brackets.
8. What is “retirement tax bracket creep”?
Increased retirement spending causes retirees to withdraw more from tax-deferred accounts, potentially moving them into higher tax brackets.
9. Why does the article expect tax rates to rise?
Out of control, growing federal debt is a convincing reason to believe future tax rates could increase. Paying taxes at today’s rates may be preferable to delaying taxes into the future.
10. How does history influence the article’s argument?
Top federal income tax rates were significantly higher during much of the twentieth century. History demonstrates tax rates can rise substantially over time.
11. What does the web page mean by saying taxes are “on sale”?
The phrase refers to the belief that today’s tax rates are extremely low compared to historical levels. Paying taxes now through strategies such as Roth conversions may reduce future tax exposure.
12. What is a Roth conversion?
A Roth conversion moves money from a traditional tax-deferred retirement account into a Roth account. Taxes are generally paid on the converted amount, but future qualified withdrawals from the Roth account can be tax-free.
13. Why might Roth accounts be more favorable than tax-deferred accounts?
Roth accounts may have the following advantages:
- Eliminate future taxes on qualified withdrawals.
- Remove concerns about future tax-rate increases.
- May prevent retiree’s tax-bracket creep.
- May eliminate or reduce taxes on social security
- Avoid Required Minimum Distributions (RMDs) for Roth IRAs.
- Provide greater certainty in retirement tax planning by eliminating tax unknowns
14. Does the web page recommend stopping all 401(k) contributions?
No. But the web page recommends focusing on ROTH 401(k) options instead of traditional tax-deferred 401(k) accounts for many pre retirees. In addition, in some circumstances, contributions to ROTH 401(k) should be limited to the amount needed to get matching contributions from the company. In these cases, the remaining money previously going to the 401(k) could be better used paying taxes to convert previous traditional 401(k) accounts to tax free ROTH accounts.
15. What is meant by the IRS being a “silent partner”?
Taxes owed on traditional retirement accounts represent an obligation to the government, your “silent partner. Since future tax laws can change, the author argues that the government’s future “share” of the account is uncertain. Your silent partner can change tax rates and get more of the account.
16. What is the article’s view on employer matching contributions?
Employees should never turn down free money, so contributing enough to get the full match is often wise. However, the matching amount is often small, often only 2 to 4 percent of salary. Contribution beyond the amount needed to get the full company match should be justified. That justification should include reviewing other options outside the 401(k) plan.
17. What disadvantages exist for traditional 401(k) plans?
Traditional 401(k) plans have the following disadvantages:
- Future tax uncertainty.
- Limited investment choices.
- Withdrawal restrictions before retirement age.
- Forced Required Minimum Distributions for traditional accounts.
- Potentially higher taxes during retirement.
- A potentially large tax bill for your children to inherit
18. Does tax-deferred investment growth outweigh future taxes?”.
Not necessarily. Although tax-deferred accounts benefit from tax free compounding, the growing tax liability to the IRS is also compounding. Combining the tax-deferred balance that belongs to the account owner with the tax liability that belongs to the IRS does not make either balance grow faster. You cannot outgrow or out compound the debt due to the IRS.
Including the balance of the account with the balance of the account that might be owed to the IRS increase the total amount to which investment management fees may be charge. Thus, the account owner could be paying management fees on some amount of the account that ultimately belongs to the taxing authorities. It is a retirement planning task to estimate taxes in retirement and determine if tax-deferred accounts are wise.
The only advantage of a tax-deferred account occurs if, when the money is withdrawn, you are in a lower tax bracket. We do not believe this circumstance is likely to happen for many people, particularly for higher net worth people.
In contrast, if the money was in a tax-free account such as a ROTH, there is more than just a tax delay, but instead a tax-free future.
19. What recommendations are made for retirement planning?
Retirement planning should consider:
- Evaluating Roth contributions or Roth conversions.
- Evaluating other tax-free plans including life insurance-based retirement planning.
- Instead of minimizing current year taxes, planning taxes over multiple years.
- Working with qualified retirement professionals, such as a CFP® and CPA.
- Considering taxes as a central part of retirement planning rather than focusing only on investment returns.
20. Should everyone convert to a Roth IRA?
Not necessarily. Whether a Roth conversion is beneficial depends on factors such as:
- Current and expected future tax brackets.
- Available funds to pay conversion taxes.
- Retirement income needs.
- Estate planning goals.
- State tax considerations.
A personalized analysis is recommended before making conversion decisions.
21. What is the overall conclusion?
Relying heavily on traditional tax-deferred retirement accounts may expose retirees to significant future tax risks. Instead rely on proactive tax planning, including the use of Roth strategies, and other tax free strategies to create greater certainty and potentially reduce lifetime taxes.
What is the Next Step to Build a Retirement Plan?
Curtis Hill, CFP, IRA and Irina Hill, CPA, IRA, are fiduciary financial advisors, they provide wealth management, investment advice, retirement planning, and life insurance. They serve in the Long Beach, CA; Lakewood, CA; Carson, CA; Bixby Hills, CA; Signal Hill, CA; and Los Angeles, CA areas. Serenity Wealth Management has extensive experience with 401k rollovers and ROTH conversions.
Go to the Calendly.com calendar link below to schedule an appointment with an expert, Curtis Hill or Irina Hill. Discover how a 401(k) ROLLOVER can enrich your retirement life for the better. Moving your 401(k) to an IRA can dramatically improve your investment options. Then moving your IRA to a Roth IRA can greatly reduce or eliminate your tax liability in retirement.


